(COOK ISLANDS FOUNDATION FORMATION)
Cook Islands Foundation
A Cook Islands Foundation is a self-owning legal entity — no trustee, no shareholders, no owner at all. It holds assets in its own name under the International Foundations Act 2012, is governed by a council the founder may sit on, and carries the same statutory creditor barriers that made the Cook Islands Trust the international benchmark: foreign judgements go unrecognised, the limitation period is short, and any fraudulent transfer claim has to clear a beyond-reasonable-doubt standard. We coordinate charter drafting, licensed Cook Islands service provider relationships, and optional company and banking pairing, from $6,500.
Core jurisdiction
Offshore Companies · Cook Islands Foundation
Asia Pacific
Cook Islands
Latitude
00.0000° S
Longitude
000.0000° W
(COOK ISLANDS FOUNDATION OVERVIEW)
A self-owning structure for protection and governance
A Cook Islands Foundation is established under the International Foundations Act 2012, among the most complete foundation statutes anywhere in the Asia-Pacific. It is neither a trust nor a company. It is a legal person that owns itself, holds assets in its own name, and is run by a council under a registered charter.With no trustee and no shareholder, the structure does not rest on the settlor-trustee relationship that gives creditors their opening in trust litigation. The founder may sit on the council and reserve powers over it — and the Act says so expressly, rather than leaving it to be argued.The foundation gets chosen over the trust in three situations: where the founder comes from a civil law country and already knows how foundations work; where the structure serves a purpose rather than named beneficiaries; and where the founder wants genuine governance involvement without the sham-trust risk. Formation starts at $6,500.
Governing law
International Foundations Act 2012
Legal character
Self-owning entity — no trustee, no shareholders
Burden of proof
Beyond reasonable doubt on fraudulent transfer
Limitation period
1 year from cause of action, 2 years from disposition
Formation time
2–4 weeks from KYC clearance
Governance
Council, optional guardian, reserved founder powers
General summary only. The Cook Islands Foundation carries the same statutory creditor barriers as the Cook Islands Trust, in a self-owning entity form. Cook Islands and Nevis are our two key jurisdictions. Suitability turns on the client, the assets and the objectives.
(WHAT IS INCLUDED)
A complete Cook Islands Foundation formation service
Pick a standalone Foundation, Foundation plus Company, or the complete Total Protection Package
Fixed fees, covering all Cook Islands government registration and first-year council costs — no hidden extras, no surprise invoices.
Cook Islands Foundation
$6,500
inclusive of all first-year fees · 2–4 weeks
A standalone Cook Islands Foundation — a self-owning entity governed by a council, with no trustee. Suits asset protection, estate planning and purpose-based structures where the founder wants direct governance involvement.
Complete application process managed on your behalf
All Cook Islands government registration and first-year council fees
Full drafting of the charter and regulations
Registered and operational Cook Islands Foundation
Foundation + Company
$7,500
inclusive of all first-year fees · 2–4 weeks + banking
A Cook Islands Foundation with an underlying LLC or IBC. The foundation is the protective outer layer; the company holds the bank and brokerage accounts, with you appointed manager for day-to-day control.
Cook Islands Foundation — registered and operational
Cook Islands or Nevis LLC or IBC — registered and operational
Full drafting of the charter and regulations
All government fees and first-year council and agent costs
Foundation + Company + Banking
$8,500
inclusive of all first-year fees · Coordinated formation timeline
The complete structure: a Cook Islands Foundation, an underlying offshore company, and a bank account at one of our partner institutions — protection, governance and working banking from day one.
Cook Islands Foundation — registered and operational
Cook Islands or Nevis LLC or IBC — registered and operational
All foundation and company formation documents
All government fees and first-year council and agent costs
Bank account at a partner institution of your choosing
Every package includes a drafted charter and regulations, registration with the Registrar of International Foundations, and direct coordination with licensed Cook Islands service providers.
(COOK ISLANDS FOUNDATION GUIDE)
Understanding the charter, the council and reserved powers
How does a Cook Islands Foundation work?
A Cook Islands Foundation is a self-owning legal person. It holds assets in its own name, and no trustee stands between the founder and those assets.
It is established under the International Foundations Act 2012. A founder executes a charter, that charter is registered with the Cook Islands Registrar of International Foundations, and the foundation comes into being as a legal entity with its own personality. It can contract, hold bank accounts, own companies and carry on business in its own name.
There are no shareholders and no beneficial owners in the ordinary sense. A council administers the foundation under the charter and, where adopted, a set of private regulations. It can be set up to benefit named beneficiaries, to carry out a defined purpose with no beneficiaries at all, or to do both.
- Charter: the registered constitutional document, setting out name, purpose and council powers.
- Regulations: private operating rules, which need not be filed with the Registrar.
- Council: the governing body, equivalent to a board of directors — minimum one member.
- Guardian: an optional supervisory role carrying powers of appointment, approval or enforcement.
We handle charter drafting, council composition, service provider relationships and registration.
Discuss your structureCan the founder sit on the council?
Yes. The Act expressly allows the founder to be a council member and to reserve powers, without the foundation being characterised as a sham.
This is the structural advantage that separates the foundation from the trust. Where a trust settlor keeps extensive powers, a creditor can argue the assets never really left their control and the trust should be set aside. The International Foundations Act 2012 tackles that risk head-on: reserved founder powers are contemplated by the statute, not merely tolerated at the edges.
Reserved powers can include amending the charter, appointing and removing council members, directing the council on specified matters, adding or varying beneficiaries, and dissolving the foundation. The charter draws the boundary, so how much control is retained is a drafting decision taken at the outset rather than an afterthought.
- Council seat: the founder can serve as a council member alongside the licensed service provider.
- Reserved powers: rights of amendment, appointment, removal and direction, all defined in the charter.
- Underlying company: the founder is usually appointed manager or director for day-to-day banking.
- Statutory backing: retained powers do not, by themselves, make the assets the founder's property.
We draft the charter so retained control and protective distance are balanced for your circumstances.
Book a consultationWhat can a Cook Islands Foundation hold?
A charter on its own protects nothing. The structure works once assets are transferred in and a bank account is open.
The foundation can hold cash and deposits, securities, business interests, intellectual property, precious metals, cryptocurrency and interests in other entities. Assets sit in the foundation's own name rather than with a trustee acting for beneficiaries — one of the practical differences clients notice first.
Most structures use an underlying company as the operating layer. The foundation owns a Cook Islands or Nevis LLC or IBC, that company holds the bank and brokerage accounts, and the founder is appointed manager or director. Real property is held through the company rather than directly, since land is always governed by the law of the place it sits.
- Cash and securities: transferred by wire or in specie, to the foundation or to its underlying company.
- Business interests: shares, LLC membership interests, and partnership interests.
- Real estate: held indirectly through an underlying company rather than by the foundation itself.
- Account opening: usually four to eight weeks, so it should run alongside formation.
We handle the bank introduction and the sequencing of transfers as part of the formation engagement.
Discuss fundingHow strong is the asset protection?
The Foundations Act carries across the creditor barriers that made the Cook Islands Trust the international benchmark.
Foreign court judgements are neither recognised nor enforced against a Cook Islands Foundation. A creditor holding a US, UK or other foreign judgement cannot put it before a Cook Islands court and have it enforced. Fresh proceedings have to be commenced in the Cook Islands, under Cook Islands law, at the creditor's own cost.
Inside those proceedings the creditor has to prove beyond reasonable doubt that a transfer to the foundation was made with intent to defraud that specific creditor — the criminal standard, applied to a civil claim. The limitation period is one year from when the cause of action arose, or two years from the date of the disposition, whichever runs out first.
- No foreign judgement recognition: the creditor begins again in Rarotonga, from nothing.
- Beyond reasonable doubt: the criminal standard, applied to a civil fraudulent transfer claim.
- Short limitation period: claims expire quickly, and once expired the transfer stands.
- Honest caveat: the foundation has a shorter adversarial court record than the Cook Islands Trust.
We will tell you plainly where the trust is the stronger option and where the foundation is.
Compare the optionsWhat is public and what stays private?
The charter is registered and public. The regulations, which hold the detail, are not.
Registering the charter with the Registrar of International Foundations confirms the foundation exists and records its name and basic framework. That is the whole of the public record. Beneficiary details, distribution provisions, council powers and operating rules can all live in the regulations, which the licensed service provider holds privately.
Reporting obligations at home apply regardless. CRS reporting attaches to financial accounts held at institutions in participating countries, and US founders have to settle the foundation's classification for IRS purposes with a qualified international tax adviser. Privacy from opposing counsel is not the same as invisibility from your own tax authority.
- Public: the foundation's name, its registration, and the registered charter.
- Private: the regulations, the beneficiary details and the internal governance arrangements.
- Two-tier design: confidentiality written into the statute, not promised by a provider.
- Reporting: CRS and home-country filings apply, and are handled properly.
We build every structure to be reported correctly where you live.
Ask about reportingWhen should a foundation be established?
During financial stability, well before any claim exists. Timing does more work here than any drafting choice.
Transferring assets into the foundation is the event that starts the limitation clock. Transfers made while no creditor claim exists are the easiest to defend and the quickest to become unchallengeable. Transfers made after a claim has crystallised draw scrutiny in the Cook Islands and, more seriously, in the founder's home courts.
Charter drafting and registration take two to four weeks once due diligence is complete. Account opening adds four to eight weeks. A structure set up today is materially stronger in three years' time than one set up the week a demand letter lands.
- Best case: established and funded years before any dispute is in contemplation.
- Workable: established during stability, with a clear and documented commercial rationale.
- Difficult: established after a claim has arisen, carrying home-court exposure.
- Total timeline: six to twelve weeks from engagement to funded and operational.
If there is an existing or threatened claim, tell us early so we can advise you honestly.
Speak to a specialistIs a Cook Islands Foundation legal, and what has to be reported?
Entirely legal. The structure is built to be disclosed, not hidden.
A Cook Islands Foundation is a lawful entity used by families, businesses and philanthropic structures worldwide. It is not a tax reduction device. Whatever tax you pay at home before establishing one, you will generally pay after it.
For US founders the foundation may be classified as a foreign trust, a foreign corporation or another entity type, depending on how the charter is drafted and how the structure actually operates. That classification drives the filing obligations, so it should be settled with a qualified US international tax adviser before the charter is finalised — not afterwards.
- Classification first: how the foundation is characterised drives every filing that follows.
- US founders: Form 3520, 5471 or other filings, depending on classification.
- CRS: account-level reporting where the foundation banks in a participating country.
- Referrals: we can introduce qualified international tax advisers from our network.
We do not facilitate tax evasion. Every structure we form is built to be reported.
Discuss complianceWho is a Cook Islands Foundation for?
Civil law founders, purpose-driven structures, and anyone who wants governance involvement without the sham-trust risk.
Clients from Germany, France, Switzerland, the Netherlands, Spain, Latin America and much of Asia already recognise the foundation from their own legal systems. For them it is the intuitive vehicle and the common law trust is the unfamiliar one. The Cook Islands Foundation gives them Cook Islands creditor protection in a form their own advisers understand.
It also suits charitable and purpose structures where no individual beneficiary needs naming, and multi-generational families who want company-style governance succession written into a charter rather than trustee administration under a deed.
- Civil law founders: European, Latin American and Asian clients who already know foundations.
- Governance-led planning: founders who want a council seat and defined reserved powers.
- Purpose structures: charitable endowments and family purposes with no named beneficiaries.
- Cost-conscious clients: a a lower entry point than the Cook Islands Trust at $10,000.
We compare the foundation against the trust in every consultation before recommending either.
Book a consultation(WHY CLIENTS CHOOSE OFFSHORE COMPANIES ONLINE)
Cook Islands Foundation formation, run on the ground in Rarotonga
We coordinate Cook Islands Foundations, Trusts, LLCs and IBCs as a single engagement. Our team sits in Rarotonga — not on the end of a referral chain.
Based in Rarotonga, on the ground
Our team works from Rarotonga, inside the jurisdiction that writes the law we rely on — not from a remote referral desk.
Direct foundation service provider relationships
Working relationships with licensed Cook Islands foundation service providers mean faster processing, better pricing, and advice grounded in local knowledge.
Charter drafting, not template filling
Council composition, guardian powers, reserved founder powers and succession are drafted around your objectives rather than pulled from a standard form.
Fixed-fee formation from $6,500
All Cook Islands government registration and first-year council fees are in the price — no hidden costs, no surprise invoices.
Honest structure recommendations
We recommend the trust where the trust is stronger and the foundation where the foundation is. The recommendation follows your objectives, not our fee schedule.
Stage 01
Transfer of ownership
The foundation owns the assets outright
Assets moved into the foundation sit in the foundation's own name. No trustee holds them for you, and they are no longer part of your personal estate.
Protective effectA creditor coming after you personally is coming after assets you no longer own.
Stage 02
No foreign judgement recognition
A foreign judgement has no force in Rarotonga
A US, UK or other foreign judgement cannot be put before a Cook Islands court and enforced against foundation assets. The creditor has to begin fresh proceedings in the Cook Islands.
Protective effectYears of foreign litigation deliver a judgement that stops dead at the jurisdictional boundary.
Stage 03
Burden of proof
Beyond reasonable doubt, on a civil claim
To set a transfer aside as fraudulent, the creditor has to prove intent to defraud that specific creditor beyond reasonable doubt — the criminal standard, inside a civil proceeding.
Protective effectMost fraudulent transfer claims are argued on the balance of probabilities. This is not that.
Stage 04
Limitation period
A short statutory window, then the transfer stands
A fraudulent transfer claim has to be brought within one year of the cause of action arising, or two years from the date of the disposition, whichever runs out first.
Protective effectOnce that window shuts, the transfer cannot be challenged whatever the circumstances.
Stage 05
Governance continuity
The council continues, the charter governs
The foundation does not hang on any one individual. If the founder dies or loses capacity, council succession follows the charter — no probate, no estate administration, no court supervision.
Protective effectForced heirship claims and contested estate administration do not reach the foundation's assets.
Stage 06
Ongoing integrity
Administration is what keeps the structure standing
Fund the foundation proactively, administer it through proper council minutes and records, and report it correctly at home. A structure thrown together once a claim has arisen is a different proposition entirely.
Protective effectThe strongest position comes from establishing early and administering with discipline.
(WHO SHOULD FORM A COOK ISLANDS FOUNDATION?)
A strong fit for civil law founders, purpose structures and governance-led planning
The foundation suits founders whose own legal system already uses them, structures built around a purpose rather than named beneficiaries, and families who want governance succession written into a charter. Where the priority is a decades-long court record against US judgment creditors, we will say so and point you at the trust.
Civil law founders, purpose structures, and governance involvement
The foundation is the natural vehicle for clients whose own legal system already uses foundations, and for founders who want a defensible seat in governing their own structure.
Civil law founders from Europe, Latin America and Asia who already know the form
Founders who want a council seat and reserved powers backed by statute
Charitable, philanthropic and purpose structures with no named beneficiaries
Families wanting company-style governance succession written into a charter
Clients after Cook Islands protection at a lower entry point than the trust
Where the court-tested record matters most
We are direct about this. The Cook Islands Trust carries forty years of adversarial testing against US judgment creditors and federal agencies. The foundation shares the statutory framework but not that case history.
US clients whose single priority is adversarial creditor protection
Situations where a decades-long court record is worth more than governance flexibility
Structures needing anti-duress provisions directing an independent trustee
Clients already comfortable with common law trust mechanics
Plenty of clients end up with both, in sequence. Read about the Cook Islands Trust, or see how the Total Protection Package combines a foundation, an underlying company, and banking.

(TOTAL PROTECTION PACKAGE)
The Cook Islands Total Protection Package
A charter on its own does nothing. The structure starts working once assets are transferred and a bank account is open. We handle the bank introduction, matching your entity profile to institutions actively onboarding Cook Islands foundations. Account opening usually takes four to eight weeks, so it runs alongside formation rather than after it.
- Cook Islands service provider application handled from first enquiry to completion
- Council, registration and third-party costs itemised in the written quote
- Charter and private regulations drafted around your objectives
- Underlying LLC or IBC formed as the operating and banking layer
- Structure registered and ready to take assets from day one
(COOK ISLANDS FOUNDATION EXPERTISE)
Meet our foundation specialists
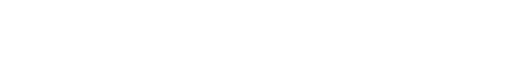
John Evans
Forbes Business Council Founder & Chief Executive Officer
Rarotonga, Cook Islands
More than two decades of experience across offshore banking, asset protection, international companies and trusts.
Melanie Tetuaiteroi
Sales Assistant
Rarotonga, Cook Islands
Supports client onboarding, communications, documentation and operational coordination, backed by fiduciary administration experience.
(FORMATION PROCESS)
01
Initial consultation
We talk through your objectives, whether the foundation or the trust fits better, your governance preferences, and your tax position at home.
02
Confirm structure and complete KYC
We settle the foundation name, the council composition, and whether an underlying company is needed, then send a tailored KYC checklist — certified passport, proof of address, source of funds.
03
Draft the charter and regulations
We work between you and the licensed Cook Islands service provider on the charter, the private regulations, council and guardian powers, reserved founder powers, and the beneficiaries or purpose.
04
Register and open banking
The charter is executed and registered with the Registrar of International Foundations, any underlying company is formed, and we run the bank introduction through to an active, funded account.
(COOK ISLANDS FOUNDATION INSIGHTS)
Cook Islands Foundation Insights
Recent Articles
Explore our latest insights, practical guides and updates on international wealth structuring.
Offshore Companies8 min read
International Company Planning: Tax, Banking, Ownership and Administration
Offshore Asset Protection5 min read
When a Cook Islands Trust Will Not Protect Your Assets
Offshore Companies5 min read
Offshore Company Annual Maintenance Requirements
International Banking & Investment4 min read
Bank vs EMI for an Offshore Company
Asset Protection4 min read
When Is It Too Late for Asset Protection?
Offshore Companies4 min read
Best Offshore Company for Consultants and Agencies
Offshore Foundations4 min read
Offshore Foundation vs Offshore Trust
Asset Protection4 min read
LLC vs Trust for Asset Protection
(ABOUT COOK ISLANDS FOUNDATIONS)
What is a Cook Islands Foundation?
A Cook Islands Foundation is a distinct legal entity under the International Foundations Act 2012. It is neither a trust nor a company: it is a self-owning legal person, holding assets in its own name and governed by a council under its constitutional documents — a registered charter and, optionally, private regulations. There is no trustee, no shareholder and no owner. The foundation legally owns its own assets.
The International Foundations Act 2012 was drafted against the Cook Islands’ established trust framework and carries its core creditor barriers across. Foreign court judgements are neither recognised nor enforced. A creditor holding a judgement from a US, UK or other foreign court cannot present it in Rarotonga and expect enforcement. Fresh proceedings have to be started in the Cook Islands, under Cook Islands law, at the creditor’s expense, within one year of the cause of action arising or two years from the date of the disposition — whichever runs out first.
Inside those proceedings the standard of proof is beyond reasonable doubt. A creditor has to establish, to the criminal standard applied in a civil claim, that a transfer to the foundation was made with intent to defraud that specific creditor. Most jurisdictions decide fraudulent transfer claims on the balance of probabilities. A great deal of the practical protection sits in the gap between those two standards.
The structural difference from a trust is that there is no trustee. In a trust, legal title passes to a licensed trustee who holds it for the beneficiaries, and a settlor who keeps too much influence hands a creditor the argument that the trust is a sham. A foundation owns itself. The Act expressly allows the founder to sit on the council and to reserve powers — amendment, appointment, removal, direction — without the assets being treated as the founder’s personal property. For founders who want real involvement in governing their own structure, that statutory permission is the whole point.
Most foundations run with an underlying company. The foundation owns a Cook Islands or Nevis LLC or IBC, that company holds the bank and brokerage accounts, and the founder is appointed manager or director for day-to-day decisions. The foundation supplies protection, perpetual duration and governance succession; the company supplies the operating layer. Real property is held through the company rather than by the foundation directly, since land is always governed by the law of the place it sits.
The honest comparison with the Cook Islands Trust: on paper the protections are near-identical, the trust has forty years of adversarial testing behind it, and the foundation does not. For a US client whose single priority is a court-tested barrier against judgment creditors, the trust is still the benchmark. For civil law founders, purpose structures, governance-led planning, and anyone weighing a $6,500 entry point against $10,000, the foundation is the better answer. We compare both in every consultation.
(COOK ISLANDS FOUNDATION QUESTIONS)
Common questions about Cook Islands Foundations
(CONTACT US)
Speak to a specialist. Let’s build your structure.
Book a confidential, no-obligation consultation with a senior member of our team to discuss your objectives and the services we have available.