
(COOK ISLANDS TRUST & ASSET PROTECTION)
Cook Islands Trust
The Cook Islands Trust is a purpose-built offshore vehicle for protecting assets, run day to day by a licensed trustee in the jurisdiction. Our team handles the setup, onboards the trustee and arranges optional company and banking add-ons, all at fixed, published fees.
Core jurisdiction
Offshore Companies · Cook Islands Trust
Asia Pacific
Cook Islands
Latitude
00.0000° S
Longitude
000.0000° W

Fixed fee from
$10,000
Stand-alone trust formation, priced up front before we start.
Typical formation
3–8 weeks
Depends on trustee due diligence, drafting and how quickly documents come together.
Primary use
Asset protection
Frequently paired with succession and long-range wealth planning.
(COOK ISLANDS TRUST OVERVIEW)
No asset-protection structure has been tested in court more thoroughly than the Cook Islands Trust, and its record across those cases has stayed remarkably strong
It is created under the International Trusts Act 1984, which hands chosen assets to a licensed Cook Islands trustee working from a deed built around your goals for protection, succession and governance.
By design it puts legal and geographic distance between you and what the trust holds. An overseas judgment carries no automatic force over the Cook Islands trustee and does not pass across control of the trust property. To get anywhere, a claimant generally has to open a new case in the Cook Islands, meet the local standards of proof and move inside tight statutory deadlines.
A protector with clearly scoped oversight powers can be named in the deed, and an underlying company often serves as the practical shell for holding bank accounts, brokerage portfolios, business stakes and other investments. Whether any of it holds up depends on setting the structure up lawfully and early, keeping the trustee genuinely independent, running the administration properly and taking suitable legal and tax advice at home.
Statute
International Trusts Act 1984, as amended
Trustee
Licensed Cook Islands trustee required
Protector
Permitted, with deed-defined powers
Redomiciliation
Foreign trusts already in place can migrate to Cook Islands law
Claim periods
One- and two-year cut-offs can come into play
Foreign judgments
Carries no automatic force against the trustee
A broad statutory summary only; how it lands depends on the deed, the transfer history, the claim and the governing law.
(WHAT IS INCLUDED)
End-to-end setup of your Cook Islands Trust
Pick only the depth of structure your situation actually calls for
Core formation of the trust starts at $10,000, a defined entry point for anyone who needs a stand-alone asset-protection vehicle. Clients who already hold workable banking or investment arrangements often take the trust on its own; others bolt on an underlying company to keep ownership of bank accounts, brokerage portfolios, business stakes or other holdings tidy.
Where a fuller, turnkey arrangement is wanted, the Total Protection option pulls the trust, the company and the banking work into one coordinated package. Which tier fits comes down to what will sit inside the structure, how those assets get managed and whether extra banking or corporate administration is in play.
The exact deliverables, outside costs and recurring trustee fees are pinned down at onboarding and written into the engagement paperwork.
Cook Islands Trust
$10,000
Typical formation: 3–8 weeks
A single-purpose asset-protection trust set up with a licensed Cook Islands trustee.
Coordination of trustee onboarding and due diligence
Trust deed and formation documentation
First-year listed formation costs
Protection with an underlying company
$11,000
Structure-dependent timing
The trust sits over an offshore company that in turn holds approved bank, brokerage or investment assets.
Cook Islands Trust formation
Underlying offshore company
Coordinated ownership documents
Trust, company and banking
$12,000
Coordinated formation
A full build tying together the trust, an underlying offshore company and banking support.
Cook Islands Trust
Offshore company
Bank-account coordination
Figures shown are indicative fixed fees in USD; the engagement letter and the trustee’s acceptance lock down the precise scope before any formation work starts.
(COOK ISLANDS TRUST GUIDE)
Understanding the Cook Islands Trust
So how does a Cook Islands Trust actually work?
It splits legal ownership and administration of the chosen assets away from whoever sets the trust up.
The settlor executes a deed and names a licensed Cook Islands trustee. As soon as accepted assets pass into the trust, the trustee holds and runs them for the beneficiaries under both the deed and Cook Islands law.
Beneficiaries, the trustee's powers, the distribution rules and any reserved powers are all spelled out in the deed. A protector can be added on top to hold defined oversight rights, without taking over the trustee's independent duties.
- Settlor: sets the trust up and puts approved assets in.
- Trustee: holds legal title to and administers the trust property.
- Beneficiaries: can take distributions as the deed allows.
- Protector: may carry limited consent or replacement powers, where the deed provides them.
We pull together the deed, the licensed trustee, the due diligence and the formation itself.
Discuss your trustSo who is actually in control of a Cook Islands Trust?
You can keep a practical hand in things, but the structure cannot leave every call sitting under the settlor's unchecked personal control.
Running the trust is the licensed trustee's job, and they have to be free to use genuinely independent judgment. The deed can still hand specific powers back to the settlor and can bring in a protector, investment adviser or company director for set roles.
The routine investment or banking activity usually runs through an underlying company, even though the trust remains the owner of that company.
- Reserved powers: can extend to limited investment, appointment or advisory decisions.
- Protector powers: might carry consent rights or the power to swap out the trustee.
- Trustee independence: remains essential to proper administration.
- Emergency planning: can spell out how authority shifts once legal pressure appears.
What can you actually put into a Cook Islands Trust?
The trust only goes live once accepted assets are properly moved in and logged as trust property.
Typical holdings run to cash, securities, private-company shares, investment accounts and stakes in an underlying offshore company. The trustee, and any bank or custodian involved, will vet the proposed assets, the source of wealth and the backing paperwork.
Real estate normally stays under the law of wherever it sits. Rather than dropping it straight into the trust, it is often held through a company or folded into separate planning.
- Cash and deposits held through approved banking arrangements.
- Investment portfolios once the trustee and custodian sign off.
- Company interests handy for pulling operating or investment assets together.
- Other property always always subject to trustee acceptance and local legal advice.
Why bother adding an underlying offshore company?
A company owned by the trust gives you a working vehicle for holding accounts, investments and other approved assets.
The trust holds the company, and directors or managers take care of the permitted day-to-day work. That keeps the trustee's ownership role apart from the everyday banking, custody and investment administration.
Our Total Protection Package ties the Cook Islands Trust to an underlying offshore company and coordinated offshore banking.
- One ownership layer across several bank, brokerage or investment accounts.
- Practical administration through authorised directors or managers.
- Continuity since the trust owns the company instead of each asset one by one.
- Separate obligations covering company filings, accounting, tax and banking compliance.
The Total Protection Package suits clients who want the trust and a workable asset-holding entity in one go.
Explore Total ProtectionWhere does Cook Islands Trust protection stop?
The Cook Islands Trust is a forward-looking planning tool, not a device for hiding assets or dodging obligations you already owe.
A transfer can be attacked if it happens after a claim has already come up, while the settlor is insolvent, or for an improper reason. The trustee will likewise insist on full disclosure of the people, the assets, the source of wealth and what the structure is really for.
The protection only stands on valid formation, genuine funding, compliant administration and advice taken in every jurisdiction that matters.
- No retroactive protection: any current or foreseeable dispute calls for legal advice straight away.
- No secrecy from authorities: tax and reporting duties continue.
- No guaranteed outcome: the facts, the timing and the governing law still decide the outcome.
- No substitute for domestic planning: insurance and local entities can still have their place.
When is the right time to set a Cook Islands Trust up?
Planning works best when it is wrapped up while your finances are steady, ahead of any particular dispute, claim or enforcement threat.
Setting the trust up means trustee due diligence, drafting, signing and funding. Leaving enough runway makes it far easier to record why the trust exists and to line up asset transfers, banking and professional advice properly.
Most formations aim for roughly 3–8 weeks, though tricky assets or banking can stretch the full rollout.
- Plan before pressure: don't leave a transfer until it turns urgent.
- Prepare documentation: keep your identity, address and source-of-wealth evidence up to date.
- Coordinate funding: settle which assets are moving before anything is signed.
- Review existing obligations: creditors, guarantees and disputes all have to be put on the table.
Which tax and reporting duties come with it?
Offshore is not the same as unreported. What you owe depends on the settlor, the beneficiaries, the trustee, the assets and the countries in the mix.
The Cook Islands trustee, plus any bank or custodian, will run KYC and beneficial-ownership checks. On top of that, your home country's tax, foreign-trust, foreign-account and asset-reporting rules may bite.
US persons can face Forms 3520 and 3520-A, along with separate foreign-account or asset reporting, depending on how the structure and accounts are set up.
- Trust reporting can be triggered when the trust is formed, funded or pays out.
- Foreign-account reporting can reach both trust and underlying-company accounts.
- Tax treatment turns on residence, control, the beneficiaries and the type of asset.
- Professional advice is best taken before you form or fund anything.
Who tends to look at a Cook Islands Trust?
It tends to appeal to people with real assets, long-term goals and a genuine need for cross-border protection or succession planning.
Think business owners, professionals, property investors, international families and anyone whose line of work draws heavy litigation risk. The upside has to be worth the setup cost, the trustee relationship and the running administration.
It fits poorly when the asset base is small, the aim is short term, full disclosure is off the table, or the settlor won't cede real authority to a licensed trustee.
- Business owners walling personal wealth off from business risk.
- Professionals with elevated liability exposure.
- Investors and families coordinating succession and cross-border ownership.
- Clients seeking Total Protection by way of a trust, a company and a banking layer.
We weigh the proposed assets, the objectives, the timing and the reporting picture before we recommend anything.
Book a consultation(WHY CLIENTS CHOOSE OFFSHORE COMPANIES ONLINE)
Cook Islands Trust know-how, based in the Cook Islands themselves
Our office sits in Rarotonga, staffed by people who have spent years across offshore trusts, companies, banking and asset-protection work. This is not a referral desk operating from afar. Being on the ground, with direct ties to licensed Cook Islands trustees, lets us run each engagement quickly and with a real feel for how the jurisdiction actually works.
On-the-ground jurisdiction knowledge
Through our Cook Islands office, clients reach a team that knows the local trustee processes, the documentation standards and what formation timelines are actually realistic.
Direct trustee relationships
We deal straight with licensed Cook Islands trustees instead of routing clients through tiers of introducers, which cuts both delay and needless referral costs.
Clear, stated pricing
Scope and fees are laid out before any work starts, and trustee charges, third-party costs and ongoing administration are all explained at onboarding.
Broader structuring experience
If the trust also needs an underlying company, banking, brokerage or a second jurisdiction, we run the whole wider build through a single point of contact.
Compliance-aware implementation
Optional legal and tax coordination can be layered on when it's wanted, so the structure is looked at next to the client's home-country reporting and compliance duties.
(HOW DOES A COOK ISLANDS TRUST WORK?)
Procedural protection for your assets
Where a Cook Islands Trust has been set up and run correctly, there is no reported instance of a creditor managing to compel a licensed trustee to hand over trust assets. The shield is at its strongest when the trust exists for a real reason and is funded well before any dispute surfaces. The statute also stacks up procedural hurdles against thin or speculative claims: a foreign judgment does not enforce itself against the Cook Islands trustee, so the creditor has to open a fresh case locally, meet the Cook Islands’ evidentiary bar and act within firm statutory deadlines. None of this makes every genuine claim hopeless, but it can shut out entirely those brought too late or unable to clear the required legal standard.
Stage 01
Ordinary operation
Practical control without personal ownership
The trust may hold an underlying company through which you direct routine banking and investment decisions. Day-to-day administration remains straightforward, while none of the trust assets are held in your personal name.
Protective effectOwnership and everyday management are separated well before the structure is ever tested.
Stage 02
Protection defined in advance
The deed defines what constitutes duress
Events such as a lawsuit, a judgment or a compelled instruction can be identified within the deed, together with the precise response the trustee is required to take should they arise.
Protective effectThe response is agreed and documented in advance, before any creditor dispute develops.
Stage 03
Trustee intervention
Control shifts when a genuine threat arises
Upon a defined event of duress, the independent trustee may suspend or assume your company-management authority and decline instructions given under legal compulsion.
Protective effectOperational control passes to the licensed foreign trustee rather than remaining with the settlor.
Stage 04
Jurisdictional separation
A foreign judgment is not automatically enforceable
A judgment obtained elsewhere does not, of itself, transfer control of the trust assets or bind a trustee acting under Cook Islands law.
Protective effectEnforceability is determined under Cook Islands law, not presumed from the foreign order.
Stage 05
Creditor procedure
A claimant must relitigate within the jurisdiction
Reaching the assets requires engaging Cook Islands counsel and commencing fresh local proceedings, subject to the jurisdiction's rules on procedure, evidence, cost and time.
Protective effectThe additional cost, delay and uncertainty can materially alter the settlement dynamic.
Stage 06
Ongoing integrity
Timing and disciplined administration sustain the protection
Fund the trust early, administer it independently, and support it with sound records, reporting and trustee oversight. Late transfers, or arrangements that retain effective control, weaken the structure.
Protective effectThe strongest position derives from early planning and disciplined administration maintained over time.
This overview is provided for educational purposes and illustrates how a properly drafted and administered structure is intended to operate. It guarantees no particular court, creditor or tax outcome. For each client, the deed, the trustee's powers, the funding history and the applicable home-country law must be reviewed.

(TOTAL PROTECTION PACKAGE)
The trust, an offshore company and banking, combined
One joined-up structure built around the Cook Islands Trust, adding an underlying offshore company and bank-account support where it makes sense. The company gives the trust an outer shell and a working entity through which approved assets can be held and administered.
- Your offshore trust application handled end to end
- First-year trustee charges and the listed third-party setup costs are covered
- The trust deed and its supporting paperwork drafted for the chosen jurisdiction
- The structure stood up and ready to take in approved assets
(COOK ISLANDS EXPERTISE)
The specialists behind your Cook Islands Trust
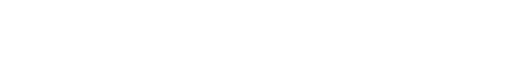
John Evans
Forbes Business Council Founder & Chief Executive Officer
Rarotonga, Cook Islands
More than two decades of experience across offshore banking, asset protection, international companies and trusts.
Melanie Tetuaiteroi
Sales Assistant
Rarotonga, Cook Islands
Supports client onboarding, communications, documentation and operational coordination, backed by fiduciary administration experience.
(FORMATION PROCESS)
01
Protection consultation
We look over your assets, current exposure, residency, family aims and timing, and weigh whether a Cook Islands Trust is a proportionate answer for you.
02
Trustee and structure selection
Working alongside a licensed Cook Islands trustee, we settle on whether you need the trust on its own, an underlying company or added banking support.
03
Due diligence and drafting
As you work through the trustee’s due diligence, we draft the deed, the powers, the beneficiary arrangements and the ownership documents that sit behind them.
04
Formation and funding
Once the trust is signed and registered, approved assets, company holdings or account arrangements are moved into the structure.
(COOK ISLANDS TRUST INSIGHTS)
Cook Islands Trust Insights
Recent Articles
Explore our latest insights, practical guides and updates on international wealth structuring.

Offshore Asset Protection5 min read
When a Cook Islands Trust Will Not Protect Your Assets
Offshore Companies5 min read
Offshore Company Annual Maintenance Requirements
International Banking & Investment4 min read
Bank vs EMI for an Offshore Company
Asset Protection4 min read
When Is It Too Late for Asset Protection?
Offshore Companies4 min read
Best Offshore Company for Consultants and Agencies

Offshore Foundations4 min read
Offshore Foundation vs Offshore Trust

Asset Protection4 min read
LLC vs Trust for Asset Protection

Offshore Asset Protection5 min read
What Assets Can a Cook Islands Trust Own?
(ABOUT COOK ISLANDS TRUSTS)
What exactly is a Cook Islands Trust?
It is an offshore trust formed under the Cook Islands International Trusts regime and run by a licensed local trustee. You, as settlor, move chosen assets in, and the trustee then holds and manages them along the lines the deed sets. That deed can name beneficiaries, install a protector, hold back defined powers and lay down rules for distributions, succession and emergency control. A trust done properly is still none of anonymous, tax-free or immune from challenge; it stays bound by trustee due diligence, whatever reporting applies and the law covering each asset underneath it.
Where the asset protection actually comes from
Legal ownership and administration are pulled away from the settlor’s own hands. A foreign claimant cannot walk up to the Cook Islands trustee with an overseas judgment and demand the assets. Any challenge has to run through the Cook Islands’ own legal framework, while the trustee keeps acting under the deed and its local duties. How well this works turns heavily on timing, solvency, disclosure, a genuinely independent trustee and assets that were really transferred. A trust thrown together only after trouble has already started can run straight into fraudulent-transfer and court challenges.
Layering in a company and a bank account
Plenty of Cook Islands Trust structures hold an offshore company, which in turn owns the approved bank, brokerage or investment assets. That keeps the day-to-day running practical while the trust stays the ultimate owner. The company, the account and the trust all have to be papered consistently, and no management power should chip away at the trustee’s independent authority. Banking, tax-residence, beneficial-ownership and financial-account reporting all keep applying. For US persons that can include foreign-trust filings such as Forms 3520 and 3520-A. Take independent legal and tax advice before you form the structure and before you fund it.
(COOK ISLANDS TRUST QUESTIONS)
Questions people commonly ask
Formed under Cook Islands law and run by a licensed Cook Islands trustee, the trust has that trustee hold whatever assets are transferred in, under the deed, for the beneficiaries and the purposes it permits.
We put stand-alone formation at $10,000 and up, with the scope and what's included confirmed before we start. Add an underlying company, banking, complicated assets or outside professional advice and the total climbs.
Figure on roughly 3–8 weeks for a typical formation. The exact pace hangs on trustee due diligence, drafting, how ready the documents are, the assets involved and whether banking or brokerage accounts are needed too.
Mostly it's used for asset protection put in place ahead of trouble. It can also carry succession, estate planning, family governance and the ownership of an underlying company or investment structure.
Defined reserved powers can be written into the deed, and a protector or investment adviser can be named. You may also stay involved day to day through an underlying company, but the licensed trustee has to keep real independent authority.
With trustee acceptance and legal advice, the trust can hold cash, securities, company interests, investment accounts and other approved assets. Real estate is usually routed through an underlying company, since the property stays under the law of wherever it sits.
The Total Protection Package brings together a Cook Islands Trust, an underlying offshore company and coordinated bank-account support. You get an outer protective layer plus a working entity for holding and administering approved assets.
Yes, so long as it's set up and used for lawful ends. It strips away none of your tax, disclosure, court or reporting duties, and it must never be used to hide assets, dodge tax or improperly beat a creditor claim that already exists.
That's a question for immediate, case-specific legal advice. Any transfer made after a claim has surfaced, or become foreseeable, can draw fraudulent-transfer, insolvency or court challenges. The structure is almost always stronger when it's built ahead of trouble.
US persons can pick up foreign-trust reporting duties, Forms 3520 and 3520-A among them. Separate foreign-account or foreign-asset reporting may also come into it, so take independent US legal and tax advice before you form or fund the trust.
(CONTACT US)
Speak to a specialist. Let’s build your structure.
Book a confidential, no-obligation consultation with a senior member of our team to discuss your objectives and the services we have available.


